It’s about to be that time; the new year, the start. We all know that means the #newyearnewme posts are about to be coming out in droves, and along with that comes the evergreen pledge to “save money.” That, much like “I wanna lose weight,” unfortunately, is a goal set up for failure. It is unachievable because it is unquantifiable. Basically, there is no real target. Save what money, how much, in what manner, and what are you gonna do with that money if you manage to keep it in your hands? The only way to answer any of these money questions is to have a plan.
The first order of business to save money is to understand what you make, and where it goes beside your savings. The name for the first step in an actual financial plan to “save money” is budget. Yes, the time has come to have that dreaded conversation, the monthly budget. It is a sad fact of our western mindset that I know immediately 33% of you tuned out. Each year that goes by means that fewer and fewer Americans utilize a budget.
Before you bolt on the whole conversation, I promise not to give you a line-item breakdown budget. In fact, I really don’t have any need to go over actual budget strategies. There are plenty of websites and books out there that will tell you HOW to budget. EveryDollar can help you make a budget based on breaking down spending intoBud percentages of your income and a tracker. This 101 guide has some tips on how to do a simple style budget that breaks things down into needs, wants, and savings. A simple google search will even tell you why you should do it. Clearly there is no need and can’t supply the want to cover the minutia of budgets here. I want to talk about the mindset issue that is behind the decline of budgeting and also holds people back from achieving their goals.
I understand the apprehension of budgets. There were a few years in my early twenties where I was obsessed with money; the whole works, making it, keeping it, growing it. It was all I read about, all I looked at, all I talked about. In simple terms, I was obsessed. I’m sure I annoyed quite a few of my friends by asking them about their financials and getting their opinions on this or that money idea. I will say that the number one thing people really don’t want to talk about is their budget.
If you want to live a better than average life, you need to act differently than the average person. Other than ordinary stands out. This could mean being abnormal like a rock star, but it can also mean being a sad clown. In reality, you will probably start out as a clown. I am not gonna ask you to don white face paint to make a budget, but you will have some sad clown moments, moments of failure. To be outside of the norm means that sometimes you will be below average. The second most people here that they panic.
“Ever tried. Ever failed. No matter. Try Again. Fail again. Fail better.”
Samuel Beckett
Do not fear to be below average. Do not fear to fail! The problem is not in failure but in failing to improve. Embrace those moments in the dumps for what they are. The beautiful thing about humanity is that we can learn from our mistakes. There is a mindset behind being at the bottom that can be massively empowering. Failing, not being a natural talent at something, or generally being insufficient means that you have something to strive towards. It gives you a path to tread. Psst… here’s a not-so-secret… The human brain thrives on the act of progress, not the achievement.
If we want to have above-average finances, we need to do things that the average American family doesn’t do, and we might as well start with a budget. While the national debt continues to climb, fewer Americans are budgeting. We all know we should do it. The issue with money isn’t the complexity of the mathematics around cash. The same is true of investment. Most investment math, (other than Quant style calculations video) isn’t much more than basic multiplication, division, addition, and subtraction. The problem with money, be that a budget or an investment is our neurological makeup and our psychology. We generally don’t have the motivation, drive, discipline, brain structures, or pick your term to stay on track and consistently show results. It isn’t just that we don’t do this with money. Generally, unless someone is forcing us to do something, many Americans struggle to accomplish something productive.
There are many causes or approaches to the problem of productivity or an errant mind. Here are a few of the resources that I would recommend starting with if you would like to take a more in-depth look into this topic: Deep Work, The 7 Habits of Highly Effective People, 12 Rules for Life, Cognitive Behavioral Therapy, The work of Jonathan Haidt, Mindfulness Meditation, Rish Dad Poor Dad, Waking Up. Many of these resources can be used for free through phone apps or your local libary and I encourage you to use free resources.
We all see this inability to complete productive tasks every day: that DIY project your husband started, the stack of jeans you were gonna sew patches into, the app you’ve been meaning to develop, the book you want to write, the workout plan and diet you know you should start… That list is starting to sound a lot like new years resolutions. The point is that I can keep generating this list forever. The common denominator is the person. The truth is that the only thing holding most of us back is that we don’t have a habit of practice.
The reason that no one manages to “save money” or “lose weight” or “find love” comes from two primary factors. Firstly, those are empty words. If I asked 10 people what it would mean to save money in practice, I would get 10 very personal and very different answers. The second is that they all reflect outcome-based thinking, not an action-based plan. Saving money is something that happens as a byproduct of acting financially responsible. Losing weight is a byproduct of going to the gym each day, and eating three healthy meals a day.
If nothing I’ve said up to this point has made it hit home yet let me run you over you with this. Your budget is a symptom of a more significant issue . The same phenomenon that keeps you from operating on a budget is the same one that makes a person light up a cigarette. You can’t stay with your budget for the same reason someone can’t control themselves when they start the seventh episode of the Witcher at 3 am even though they have to be at work in two hours. The neurological structures that don’t let you stick with your budget each month are the same as the ones that drive a gambler to spend their last time trying to feel the joy of winning. What causes you to skip your budget meeting for the month, just this once, is the same as what causes someone to allow for that cheat day Big Mac that breaks their diet streak.
You have a destructive habit that society commonly calls an addiction. This particular addiction is behavioral. Don’t worry, I have it too. We all do really because the human brain is wired to reward us basically for not dying at this moment and “feeling good.” We recognize smoking as an addiction, as being medically obese as an illness, video game addiction is even becoming a popular area of psychology. Avoiding financial responsibility is an addiction: a habit, or a pattern of behavior with continually increasing consequences for your future self.
I am not saying you need a doctor, not in the least. All of the addictions I listed before can be solved without medical intervention. What you need is to build a practiced life, a life that you structure so that you can live in the manner which you desire. To act financially responsible starts with changing the mindset you have about how you live your life. It’s time to live your life intentionally. In the world of finance, intentional living starts with a budget.
To run our lives with a budget, we are gonna have to give up a few social stigmas, and a few of the ideas we have about our experience. One of the primary reasons that people in American society don’t have success with their budgets is because our culture is private about finance. Go ahead and ask one of your close friends how much they make a paycheck or a year, and how they spend it. That conversation will get very uncomfortable, really quickly. No one wants to talk money, and that is really only holding us back. Finances are a fact of life and one that we need to get comfortable talking about. We have grown to share our mental states, our bouts with depression or anxiety, and the acceptability of reach out for assistance with our friends. Yet, financial status is taboo. Why? This isn’t very smart. We need to have real conversations about where we are at with our money, month to month expenses, retirement, housing investments, or mortgages; the whole thing. Part of the reason that people struggle with money is that we don’t openly discuss what is beneficial and what is detrimental.
In all my time studying money, I found that people predominantly use two excuses to explain why they can’t, won’t, or don’t need a budget. The first way is to say that they don’t want to be constricted by a budget. The second is that they don’t feel they need to do it because things are going fine. Sometimes there will be a bit of bleed-over between the two, but let me demonstrate the underlying principles that govern this kind of financial behavior.
A budget doesn’t say that you have to change anything about the way you live. You can still go out to eat the exact same amount. You can again party with your friends the exact same amount. You can continue to “toss dem dollas and watchin’ dem cheeks clap at da club,” if you so wish. The first step in making a budget is to create a record that tells YOU where you spend your money. You can make a financially irresponsible budget. Your budget can exactly match your current spending. From there, use it to track that your debaucheries don’t get out of hand. Keep them bottles poppin’. Keep all your parties and fine dining and club going and whatever else budgeted in. I don’t recommend it, as retirement is probably more important than “stuntin on dem hoes.” What is interesting is that the person who doesn’t want to be constricted wouldn’t recommend their current budget either.
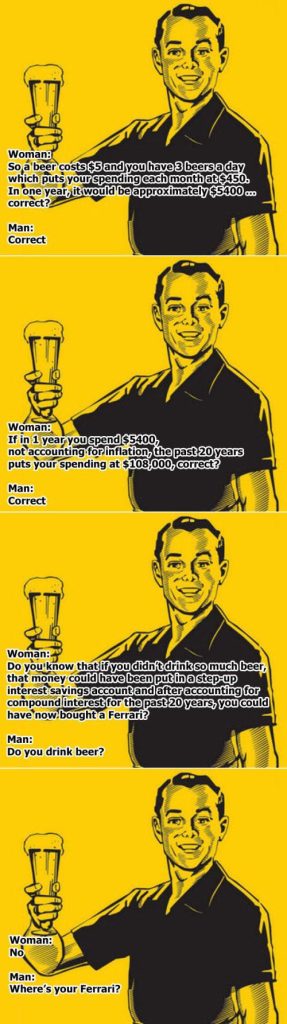
The reason the person that doesn’t want to be constricted won’t make that budget is actually the same as the person who “feels” they are doing fine. The “Fine” person lives each month, makes decent money, pays bills, eats well, and lives the life they “want” without a budget. What do they need one for? They put $50 in a savings account each month. They contribute to their 401k. Interestingly both of our people are in this meme style comic.
That "fine" person won't make a budget for the same reason that the woman in the Ferrari joke didn't. They don't want to know how much money they spend on things that they know to be wasteful in the long term. The man in the joke did realize he drank his Ferrari in beer because he didn't want the budget to tell him he could have a Ferrari. He is the person that won't be constricted by a budget. He didn't want to be squeezed by his own values, in this case, beer over Ferrari. The woman in the joke is our second scenario. She didn't budget because she didn't want to know that between her hair and nails, her BMW lease, and the designer bag she bought on a whim actually cost three times as much as the man's drinking habit. She could have a couple Ferarri's and have lost her terrible attitude. Both people are willfully choosing to be ignorant of their finances, and that's because the alternative is hard.
If you have ever tried dieting, working out, quitting smoking, or any other significant change in your behavior, you understand that it’s incredibly hard. The same is true for a budget. It’s going to point out all the flaws in the way you spend money. It does this because they weren’t that hard to see in the first place you just weren’t looking. It doesn’t take a whole lot of mental fire-power to balance what comes in with what goes out. What it does take is commitment. It takes effort. More than anything, it takes consistency over time.
This is the key to success in anything. In the book Holes, as Stanley digs his first hole the other boys tell him, “The first hole’s the hardest.” That is true of the first day in any major change. Then they say oh no-no, the second hole is the hardest, then the third, then the fourth and so on. The paradox is that while the boys are all counting up for Stanley, they don’t consider the hole they are about to dig to be the hardest. What is vital to recognize is that none of the boys think their NEXT hole is the hardest. After some time, the next hole is actually natural. This is because you’ve gotten into practice.
This is the making of consistency. This is how a budget works. The first month is gonna be hard. Shoot, the first day is gonna be hard. You’re gonna feel that constriction. You’re gonna feel the knowledge that you are the person that wastes too much money on fast food, or clothing, or whatever it may be. More than anything, you’re gonna feel uncomfortable. You’re gonna feel out of place, itchy, jittery and restless. You are gonna want to bolt right back into your comfortable habits. The second day is gonna be even harder. Each day in that first month is going to be a progressively worse struggle. The same as each day is when you start working out or dieting or quitting smoking. Staying the course is a matter of recognizing that you’re building a practice. The next hole is what matters.
Another way to help with this is to develop other practices. It might seem crazy, but the human body can practice getting better at the art of practicing. This is what we need to start to leverage to get over these initial days. We aren’t quitting smoking, being out of shape, or being financially irresponsible. We are becoming a non-smoker, being fit, and becoming financially responsible. We are building new habits in our life. Like muscle memory for sports, your brain also develops and adapts to what you repeatedly do. Allow yourself to fail. From there, “fail better.” The first month won’t be perfect but stick with it. If you get 5% better each month, you’ll be a pro in less than two years. Imagine being comfortably in complete control of your finances in two years! The goal isn’t just to be building wealth but to be comfortable while doing it, even in the uncomfortable moments. Best of luck in the new year, and I hope you all accomplish your goals.

